



DGT: SPP-TDLN Data Collection Not for Monitoring Taxpayers‘ Accounts
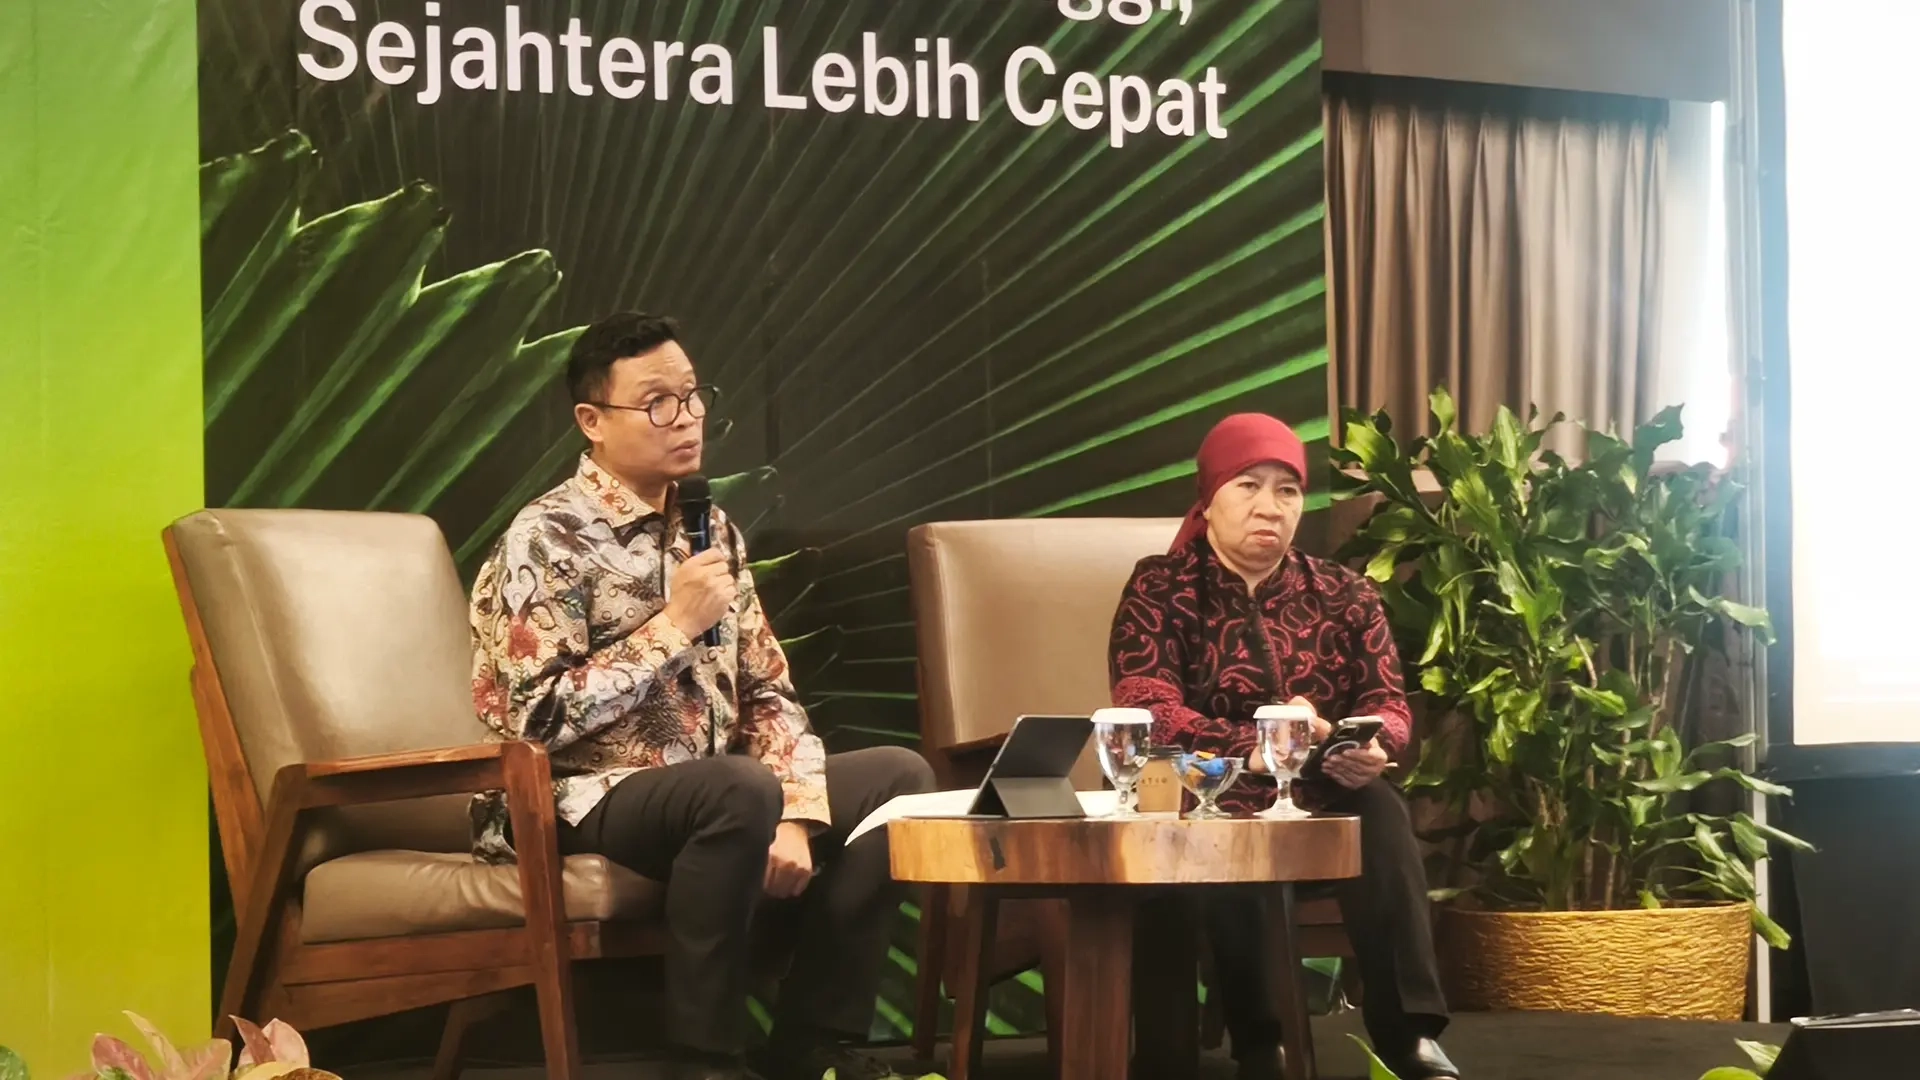
JAKARTA, DDTCNews - The Directorate General of Taxes (DGT) has affirmed that all cross-border transaction data will be used on a limited basis by the operator of the tax collection system for cross-border digital transactions (sistem pemungutan pajak atas transaksi digital luar negeri/SPP-TDLN in Indonesian).
Director General of Taxes Bimo Wijayanto stated that a range of taxpayer data, including identity, account numbers, and transaction amounts, will be managed to map and analyse transactions subject to VAT. However, the DGT will not automatically use such data to deliberately monitor taxpayers' accounts.
"Data governance is used on a limited basis for mapping, analysis and VAT collection. This system is not intended in any way to monitor the public's accounts," he said, as quoted on Monday (5/10/2026).
Pursuant to Presidential Regulation No. 68/2025, the government has appointed PT Jalin Pembayaran Nusantara as the SPP-TDLN operator. The technical rules for VAT collection through the SPP-TDLN mechanism are set out in detail in Ministry of Finance Regulation (MoF Reg.) 49/2026.
Referring to MoF Reg. 49/2026, VAT becomes payable at the point when the SPP-TDLN operator provides confirmation to another party that VAT applies to the cross-border digital transaction in question.
The term "another party" refers to a party directly involved in or facilitating transactions between transacting parties, appointed by the minister of finance to withhold or collect VAT on cross-border digital transactions.
In the operation of the SPP-TDLN, other parties are required to submit tax-related data to the SPP-TDLN operator. That data will be confirmed by the SPP-TDLN operator as to whether the cross-border digital transaction concerned is subject to VAT or not.
Pursuant to Article 8 paragraph (3), paragraph (4) and paragraph (5) of MoF Reg. 49/2026, the tax-related data to be submitted includes, among others, the entrepreneur's name, transaction amount, transaction currency, destination transaction type, account number and other details.
The SPP-TDLN operator must provide confirmation no later than 1 day after the other party requests it. The SPP-TDLN operator must also manage and maintain the security and confidentiality of the data for which confirmation is requested.
"The SPP-TDLN operator is responsible for the management, security, confidentiality and protection of data referred to in Article 8 paragraph (3), paragraph (4) and paragraph (5)," reads Article 9 paragraph (1) of MoF Reg. 49/2026.
For information, the government has appointed 6 parties as other parties tasked with collecting VAT under the SPP-TDLN scheme. The six comprise 5 SOE banks, namely BRI, Mandiri, BTN, BNI and BSI as well as 1 fintech company, PT Fintek Karya Nusantara (LinkAja).
Bimo noted that the SPP-TDLN was officially implemented on 25 September 2026. The 6 other parties then commenced collecting VAT on overseas digital transactions from 1 October 2026. (rig)