



Entities to Register as GloBE Taxpayers & File Returns, No Delegation
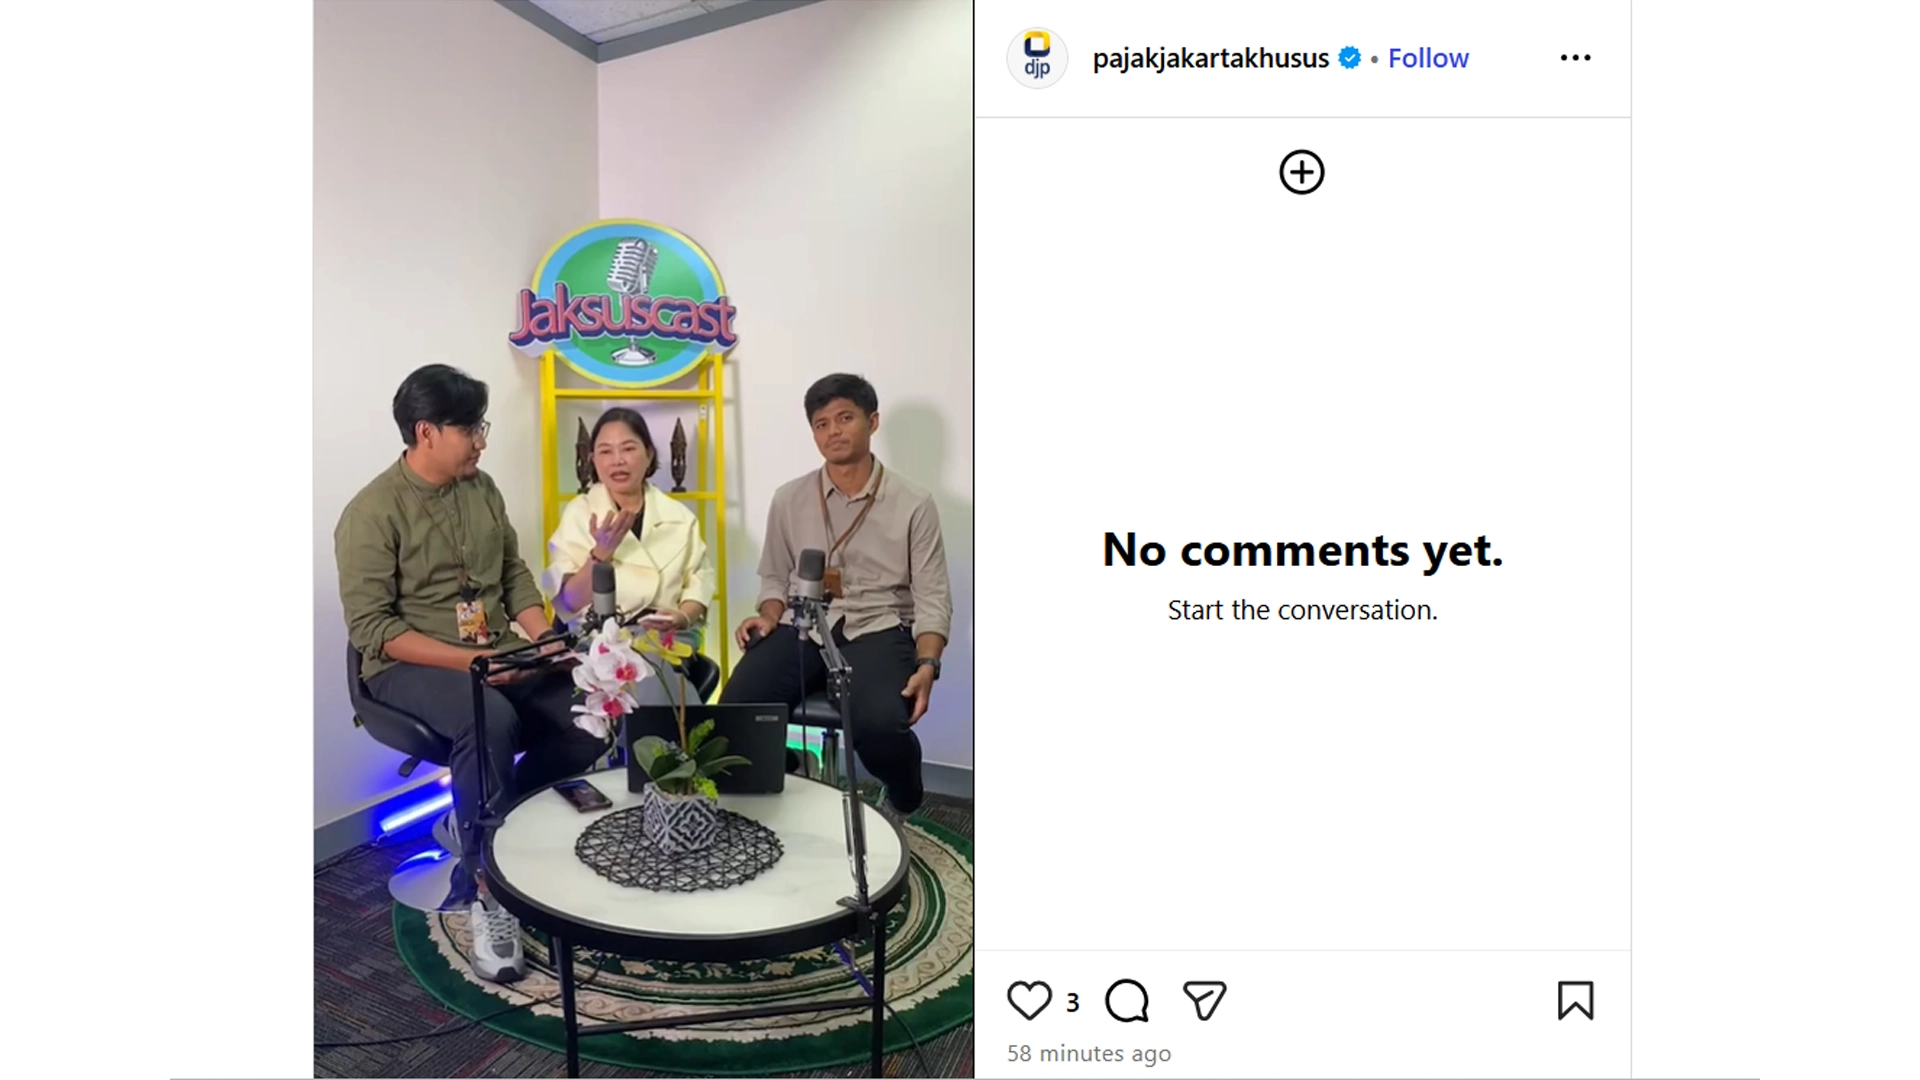
JAKARTA, DDTCNews - The Directorate General of Taxes (DGT) has reiterated that the addition of GloBE taxpayer status cannot be delegated to a single constituent entity.
Tax Instructor at the Special Jakarta Regional Tax Office, Fransiska Yansye, said that the addition of GloBE taxpayer status must be carried out by all constituent entities that are members of a GloBE-covered multinational enterprise (MNE) group.
Although some countries allow a constituent entity to delegate GloBE taxpayer registration administration to a constituent entity acting as a representative, she stated that Indonesia does not adopt such a scheme.
"For example, if there are 3 subsidiary constituent entities in Indonesia, all 3 entities must register once the ultimate parent entity has consolidated EUR750 million. There is therefore no lead entity, each is individually responsible for its own obligations," said Siska on the podcast entitled Jaksuscast, Tuesday (22/9/2026).
Not only must each constituent entity add GloBE taxpayer status, but every constituent entity that is a member of a GloBE-covered MNE group must also file an income tax return in relation to GloBE. As with the registration, the filing of a GloBE income tax return on behalf of several constituent entities cannot be delegated to just one constituent entity.
"All group members must register, not just one. There is no lead entity. Each will also file their own GloBE income tax return individually, not a single combined one," said Tax Instructor at the Special Jakarta Regional Tax Office Kukuh Wahyu Nugroho.
Before adding GloBE taxpayer status, a constituent entity of an MNE group must first confirm whether the group is indeed covered by GloBE.
Pursuant to MoF Reg. 136/2024, an MNE group falls within the scope of GloBE if the group's annual revenue reaches EUR750 million based on the consolidated financial statements of the UPE in 2 of the 4 years preceding the GloBE imposition year.
Constituent entities that are members of such a group must complete the addition of GloBE taxpayer status no later than 9 months after the end of the first GloBE imposition year.
For example, if a multinational enterprise group has a minimum revenue of EUR750 million in at least 2 years within the 2021-2024 period, that group becomes subject to the global minimum tax from the 2025 imposition year as the first year.
Constituent entities that are members of a group whose first imposition year is 2025 must add GloBE taxpayer status no later than 9 months after the end of the 2025 imposition year, that is, by September 2026.
The addition of GloBE taxpayer status may now be carried out via the coretax system using the taxpayer account of the person in charge (PIC) of the constituent entity.