



Complex Transfer Pricing Disputes: The Crucial Roles of MAP and APA
SINGAPORE, DDTCNews – The Mutual Agreement Procedure (MAP) and Advance Pricing Agreement (APA) are two important instruments in both preventing and resolving international tax disputes, particularly those relating to transfer pricing (TP).
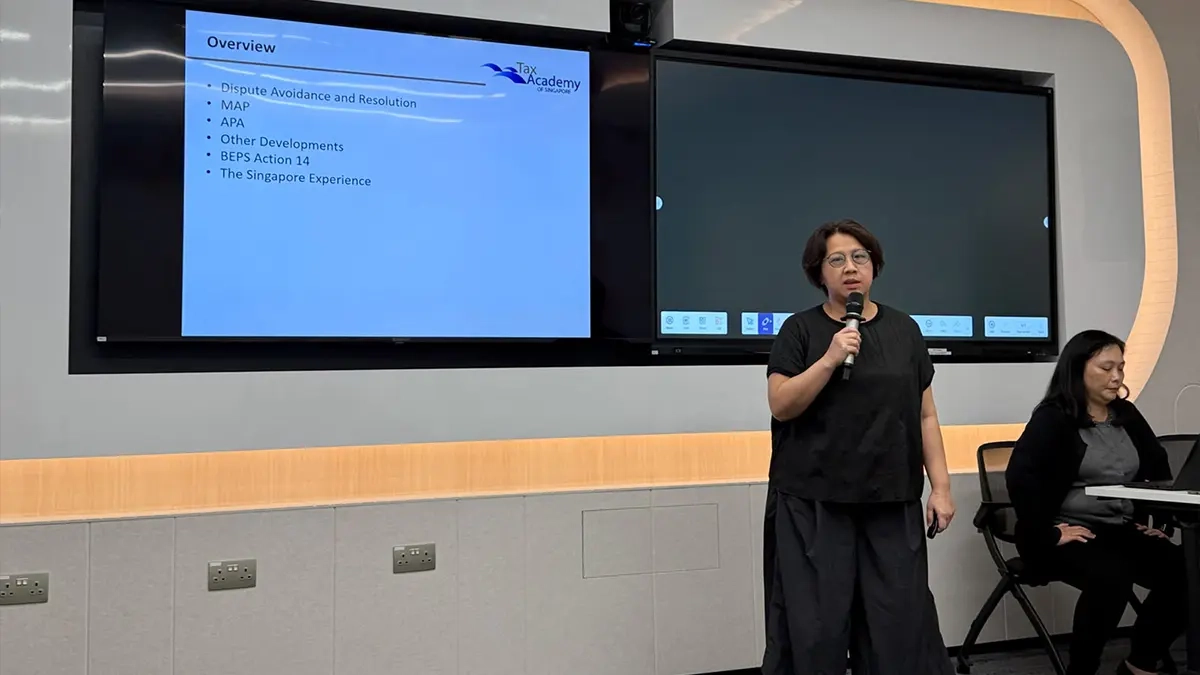
This was among the topics discussed in the Dispute Avoidance and Dispute Resolution session presented by the Head of Transfer Pricing and Dispute Resolution Branch of IRAS, Ng Pei San, and Senior Lecturer from Nanyang Technological University (NTU), Jow Lee Ying.
At the WU-TA Advanced Transfer Pricing Programme 2026 in Singapore, both speakers discussed the mechanisms of MAP, APA, arbitration, dispute resolution, BEPS Action 14 and Singapore's experience in preventing and resolving tax disputes.
In their presentation, Ng Pei San and Jow explained that tax dispute resolution can be pursued through various avenues, covering both dispute prevention and dispute resolution orientations.
For prevention, the available instruments include unilateral APA as well as bilateral or multilateral APA. Meanwhile, disputes that have already arisen can be resolved through domestic proceedings, MAP or arbitration under certain conditions.
MAP Mechanism
MAP is a mechanism available under a tax treaty and operates independently from domestic legal remedies.
Through MAP, the tax authorities of treaty partners endeavour to resolve differences or difficulties relating to the interpretation or application of provisions in a tax treaty based on mutual agreement.
MAP may be initiated where the action of one or both countries results in, or is likely to result in, taxation that is inconsistent with the provisions of the tax treaty.
Accordingly, MAP may be used both where tax has already been imposed and where it remains potential. Ng Pei San and Jow also clarified that initiating MAP does not require double taxation to have already occurred.
In this process, the Competent Authority (CA) plays a pivotal role. The CA will consider whether the objection raised by the taxpayer is justified and will proceed with discussions with the CA of the treaty partner, provided the requirements are fulfilled.
Both CAs then determine their positions based on each country's domestic legal provisions and the provisions of the tax treaty. In conducting negotiations, the CA is also obliged to endeavour to reach a resolution based on best endeavours.
However, this principle does not imply that both CAs must always reach agreement. The final outcome may involve full or partial elimination of double taxation. Double taxation may also persist if the two CAs fail to reach agreement.
On the other hand, initiating MAP does not automatically preclude dispute resolution through domestic proceedings. Ng Pei San and Jow explained that a taxpayer may pursue domestic proceedings and MAP simultaneously.
In practice, there are several approaches that a CA may adopt, including suspending MAP discussions until domestic proceedings are concluded or continuing MAP subject to certain conditions. Taxpayers may also utilise a protective appeal within domestic proceedings.
Accordingly, taxpayers need to understand the redress options available to them and the approach adopted by each CA. According to the OECD, domestic legal proceedings can generally be suspended to allow room for resolution through MAP.
Where MAP has not produced agreement, an arbitration mechanism is also available under certain conditions. Ng Pei San and Jow explained that arbitration may be used to resolve issues that remain unresolved where the CAs have been unable to reach agreement within 2 years.
A taxpayer that has previously initiated MAP may request in writing that unresolved issues be submitted to arbitration. This mechanism does not require prior consent from the CA, provided procedural requirements have been met.
However, arbitration applies only to unresolved issues and is not an alternative or additional avenue to MAP.
An arbitration decision is in principle binding on both countries, with certain exceptions, for example, where the taxpayer does not accept the decision, or where the decision is found to be unenforceable by a court of one of the countries due to a breach of the arbitration provisions or procedural rules.
APA Mechanism
In addition to MAP, APA is an instrument oriented towards preventing transfer pricing disputes. An APA refers to an agreement between a tax authority and a taxpayer or between 2 or more tax authorities, concerning the transfer pricing methodology and the pricing of specific related-party transactions. Depending on the number of tax authorities involved, an APA may take the form of a unilateral, bilateral or multilateral agreement.
An APA can offer a number of benefits, including reducing transfer pricing compliance costs in the long term, providing certainty over covered transactions, proactively preventing TP disputes and affording a means of resolution for complex or high-risk TP issues.
However, the APA process also requires substantial time and resources. Taxpayers are required to submit detailed information to the tax authority before an agreement is reached.
The bilateral APA (BAPA) process also tends to be more complex than a unilateral APA (UAPA), as it involves tax authorities from two jurisdictions.
Ng Pei San and Jow identified a number of conditions that may be considered as grounds for pursuing an APA. These include a high risk of TP audit, the availability of an APA programme or legal basis, the existence of a tax treaty for BAPA purposes, complex or high-value transactions and issues that can be substantiated with robust facts and analysis.
Developments in Dispute Resolution
Beyond MAP and APA, developments in international tax administration cooperation have given rise to further instruments aimed at providing certainty while reducing the potential for disputes. In this context, Ng Pei San and Jow also discussed the International Compliance Assurance Programme (ICAP) and joint audits.
ICAP is a voluntary programme for multilaterally assessing and providing assurance on the tax risks of multinational enterprises.
The programme aims to provide a faster and clearer pathway to tax certainty whilst fostering a cooperative relationship between taxpayers and tax administrations. Singapore itself began participating in ICAP in 2021 as a non-lead covered tax administration.
Meanwhile, joint audits combine elements of information exchange, simultaneous tax audits and overseas tax audits. This mechanism is designed to enhance international cooperation among tax administrations.
In line with the development of these various instruments, efforts to strengthen dispute resolution mechanisms have also been pursued at the global level through BEPS Action 14.
BEPS Action 14 is directed at improving the effectiveness and efficiency of MAP, whilst minimising undesirable uncertainty and double taxation.
Countries have committed to meeting minimum standards, including implementing MAP in good faith, resolving cases in a timely manner, applying administrative processes that support the prevention and resolution of tax treaty-related disputes and providing access to MAP for taxpayers that fulfil the requirements.
This implementation is complemented by a peer-based monitoring mechanism through the Forum on Tax Administration (FTA) MAP Forum.
Report from Singapore
For information, this report was written by DDTC Consulting Specialist Ngurah Bagus Pembayun Kepakisan, who is attending the WU-TA Advanced Transfer Pricing Programme 2026 in Singapore. The programme is held from 28 September to 1 October 2026.
In addition to Bagus, there are 5 other DDTC professionals participating in the programme. The participation of these professionals in the training forms part of the Human Resource Development Programme (HRDP) run by DDTC.
Through this programme, DDTC provides its professionals with the opportunity to develop their competencies through various training programmes, both domestically and overseas. All costs of participation in this programme are borne by DDTC with no service bond attached.
DDTC Founder Darussalam, who is also one of Indonesia's leading tax experts, stated that the participation of DDTC professionals in the programme is aimed at strengthening their understanding of developments and practices in transfer pricing at the international level.
In his view, the knowledge and perspectives gained from this international training will support DDTC professionals in handling a wide range of transfer pricing issues and in providing services and advisory to clients to a standard that exceeds expectations.
Participation in this international training programme also forms part of DDTC's commitment to continuing to invest in its human resources. This investment is made through various competency development programmes, including professional training and the provision of scholarships for study at leading universities worldwide.
This commitment is in keeping with DDTC's vision of becoming a tax institution grounded in research, technology and knowledge that sets the standards and beyond. (rig)