



Digital Economy Taxation Dynamics Through a Transfer Pricing
SINGAPORE, DDTCNews – The debate on the taxation of the digital economy is not new. It has been ongoing since at least 2015, particularly in relation to BEPS Action 1. This means the issue has been attracting attention for roughly a decade.
Over that period, numerous developments and dynamics have emerged in international tax rules, ranging from the withdrawal of the European Union's digital services tax (DST) proposal, the adoption of Article 12B in the UN Model Convention, the implementation of Pillar Two and the side-by-side agreement, to the United Nations' latest publication on the revised UN Framework Convention on International Tax Cooperation (UN FCITC) accompanied by two draft protocols.
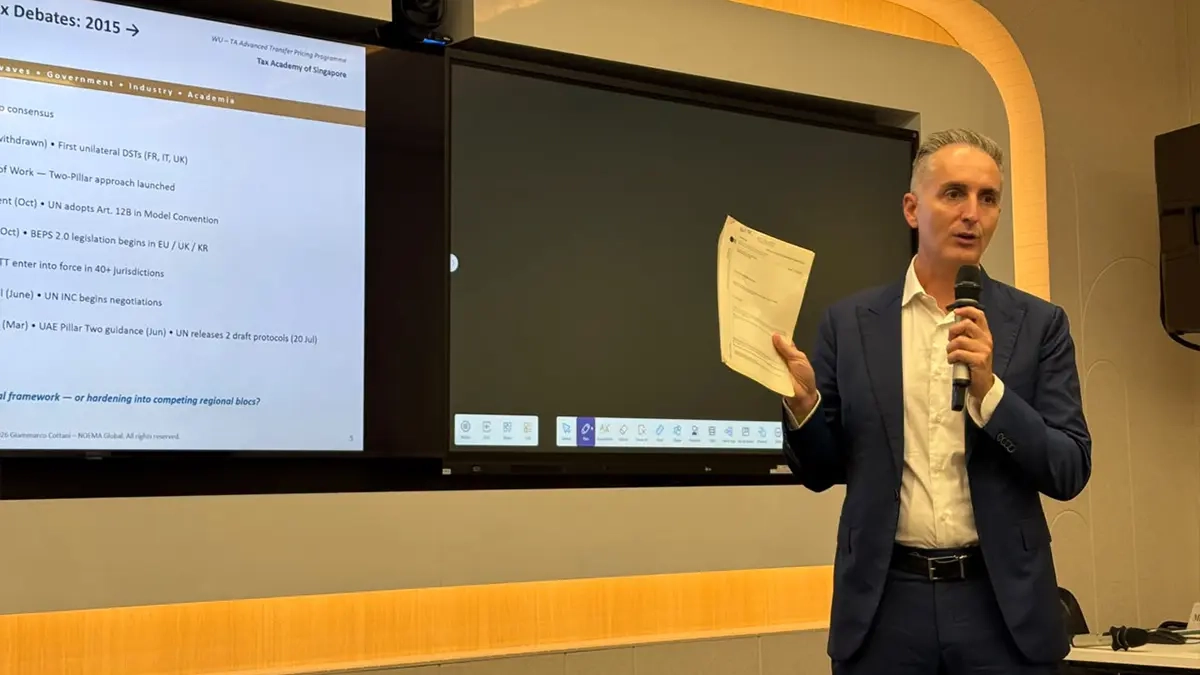
These developments and dynamics formed the opening of the material presented by Founding Partner of NOEMA Global Tax & Policy, Giammarco Cottani, at the WU-TA Advanced Transfer Pricing Programme 2026 in Singapore.
Developments in the Two-Pillar Solution
Drawing on these developments, Cottani divided his material into 5 main topics. The discussion began with an examination of why digital issues remain relevant today, followed by an overview of the various digital business models.
He also reviewed the latest issues in digital business taxation, the changing tax landscape following the expansion of global discussions and how multinational enterprise (MNE) structures may adapt in response to these regulatory dynamics.
Cottani explained that international tax developments concerning digital businesses remain dynamic. Pillar Two is currently entering the enforcement stage, whilst Pillar One, which is aimed at addressing the taxation of digital businesses, is still being discussed at the conceptual level.
“Pillar One is still at a very general level, as you will see. This is because there is as yet no agreement among the key countries, particularly the US, on whether greater taxing rights should be allocated to source countries or market countries when a multinational group participates in the economic life of a country without a physical presence there,” he said.
As matters have progressed, the digital business taxation landscape has become increasingly fragmented due to fundamental differences in views among key authorities. As a result, the policies being pursued have become overlapping.
“In my view, this fragmentation has given rise to a number of policy tracks running in parallel and overlapping at present, i.e., Pillar Two, the UN Framework Convention and unilateral DSTs/withholding taxes, which in international tax policy, are all attempting to address the taxation of digital businesses,” he said.
Cottani identified at least 3 issues with the implementation of Pillar One. First, the application of Amount A causes a country's domestic rules to set aside the arm's length principle (ALP) or permanent establishment (PE) concept, since its allocation is based on certain criteria that are very formulaic.
Second, the provisions in Article 7 of double taxation agreements (DTAs) need to be adjusted, as the application of Amount A does not follow the traditional approach currently provided for under Article 7 or Article 9 of DTAs.
Third, the application of Amount A requires countries to sign, ratify and bring into force a multilateral convention.
Digital Business Through a Transfer Pricing Lens
Having discussed global policy developments, Cottani then examined the characteristics of digital businesses from a transfer pricing perspective. He noted that, broadly speaking, there are at least 5 main types of digital business model in existence today.
These five main types of digital business models are: online advertising or social, software as a service (SaaS) or cloud, marketplaces or platforms, digital content or streaming and fintech or online payments.
Cottani explained that all five business models share 2 principal characteristics. First, a high degree of reliance on intangibles, such as technology, data, brands and network effects. Second, limited physical presence in market jurisdictions.
Both of these characteristics give rise to challenges for the traditional approach to allocating taxing rights based on PE and transfer pricing.
However, Cottani also highlighted that any analysis of value allocation in digital businesses must begin by questioning where value creation occurs.
“Among these various models, which ones create value primarily where users are located and which ones create value primarily where developers are located?” he remarked.
As such, what is the relationship between digital businesses and value creation or supply chains from a transfer pricing perspective? According to Cottani, 2 approaches can be used.
The first approach is the traditional transfer pricing or DEMPE perspective. Under this approach, the key aspect to consider is the location of the people performing significant functions.
“Value is created where people perform significant functions,” he explained.
However, as digital business models have evolved, value creation can also occur where users interact, generating data and network effects as well as at the location of consumption and advertising markets or where local marketing functions and regulatory access are available.
This perspective then led the discussion to the second approach, namely the market or user-participation lens. According to Cottani, in the context of digital business models, the focus is beginning to shift from the first approach towards the second.
MNE Responses to Developments in Digital Business Taxation
Having explained the shift in perspective on value creation, Cottani then set out how multinational enterprises (MNEs) are responding to these developments. Based on his observations, there are 6 changes that are beginning to emerge in MNE tax planning.
First, re-onshoring of intellectual property (IP). According to Cottani, MNEs are beginning to relocate intellectual property away from low-tax jurisdictions.
Second, principal to limited-risk distributor (LRD) conversion. In this context, MNEs are seeking to strengthen substance at the local marketing level by converting principal functions, particularly by utilising Amount B provisions where available.
Third, local marketing or data substance. Cottani views this as one of the MNE responses to heightened scrutiny from tax authorities in a number of countries.
This is achieved by identifying the existence of genuine marketing intangibles. This can provide a basis for justifying above-market returns and managing potential disputes with local tax authorities.
Fourth, passing on digital services taxes (DST). Cottani cited technology companies such as Google, Amazon and Apple, which have responded to DST policies by passing on the tax through charges to business-to-business (B2B) clients, such as advertisers or third-party sellers.
In connection with this practice, he also highlighted the risk of cascading, since DST is generally levied prior to value added tax (VAT).
Fifth, treaty most-favoured-nation (MFN) and PE hygiene. According to Cottani, MNEs are increasingly reviewing their operational structures, including the use of contract managers rather than employees within SaaS sales teams, in order to manage the risk of creating a permanent establishment (dependent-agent PE).
Further, MNEs are becoming more astute in utilising MFN clauses in DTAs to obtain lower withholding tax rates, particularly in relation to Article 12B of the UN Model Tax Convention.
Sixth, governance and Pillar Two data. Cottani stressed the importance of MNEs building their internal capacity to ensure data completeness in order to make use of the transitional country-by-country reporting (CbCR) safe harbour.
In his view, data readiness remains critical even where a multinational group falls within the scope of an exclusion under the side-by-side agreement. A number of jurisdictions in which MNEs operate, such as the United Arab Emirates, Singapore, Ireland and Switzerland, have made such data completeness mandatory since fiscal year 2024.
In the closing session, Cottani observed that the debate on digital business taxation has become one of the key drivers of international tax reform.
However, against the backdrop of the continued absence of agreement on Amount A and the widespread unilateral implementation of DSTs, the UN initiative has also emerged as one of the tracks that MNEs need to monitor when analysing the impact of various international tax policy developments.
Cottani also advised MNEs to move promptly to establish substance aligned with DEMPE principles, manage the risk of marketing intangible claims in market countries and strengthen Pillar Two governance at an early stage.
He further emphasised that the added value of a tax adviser is increasingly determined by the ability to understand and navigate 3 frameworks operating in parallel, namely the OECD, the UN and unilateral policies.
Such capability is necessary for companies to understand the tax consequences of the various overlapping frameworks whilst also managing the impact on business operations and cash flows.
Report from Singapore
For reference, this report was written by Senior Specialist at DDTC Fiscal Research & Advisory Rinaldi Adam Firdaus, who attended the WU-TA Advanced Transfer Pricing Programme 2026 in Singapore. The programme was held from 28 September to 1 October 2026.
In addition to Rinaldi, 5 other DDTC professionals took part in the programme. Their participation in the training forms part of the Human Resource Development Programme (HRDP) run by DDTC.
Through this programme, DDTC provides its professionals with the opportunity to develop their competencies through various training programmes, both domestically and overseas. All costs associated with participation in this programme are borne by DDTC without any service bond.
DDTC Founder Darussalam, who is also one of Indonesia's leading tax experts, stated that DDTC professionals' participation in the programme is intended to strengthen understanding of developments and practices in transfer pricing at the international level.
He noted that the knowledge and perspectives gained from international training of this kind can support DDTC professionals in handling a wide range of transfer pricing issues and in delivering services and advisory to clients to a standard that exceeds expectations.
Participation in the international training programme also forms part of DDTC's commitment to continued investment in human resources. This investment is carried out through various competency development programmes, including professional training and the award of scholarships for study at leading universities around the world.
This commitment is consistent with DDTC's vision of becoming a tax institution grounded in research, technology, and knowledge that sets high and enduring standards. (rig)