



Suahasil on 2026 State Budget Law Granting Tax Refund Audit Powers
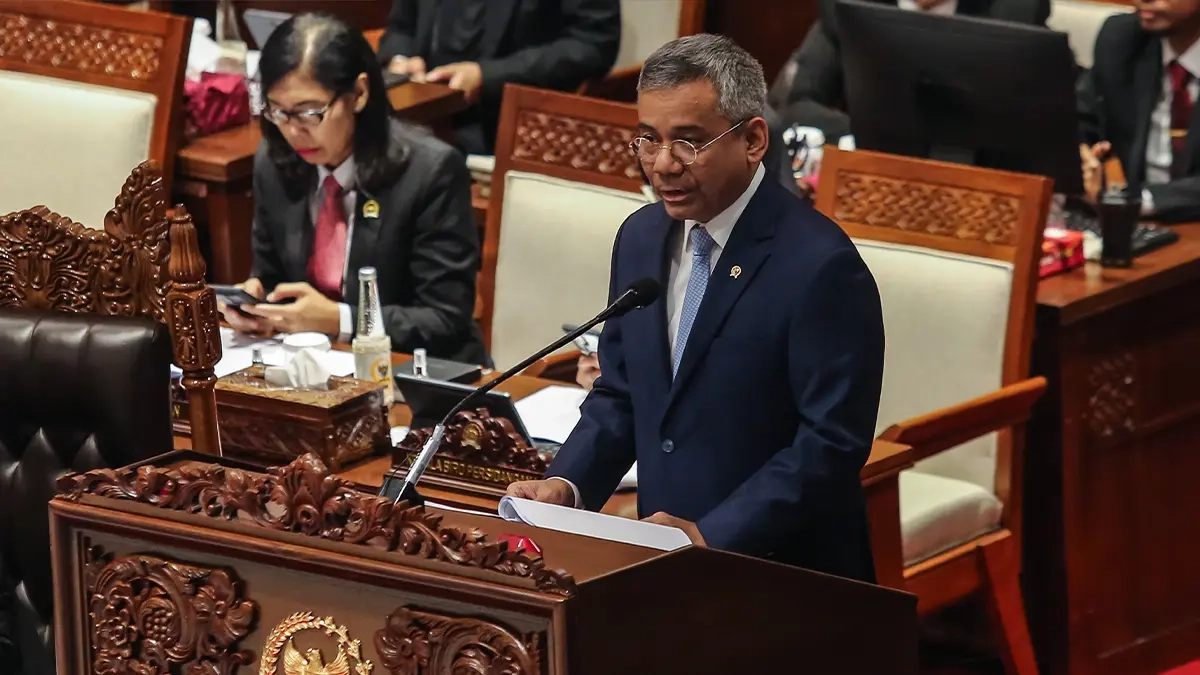
JAKARTA, DDTCNews - The 2027 State Budget Law, approved by the House of Representatives, includes provisions granting the Minister of Finance authority to conduct special audits on tax refunds.
The authority to conduct special audits on tax refunds is set out in Article 37 paragraph (1) of the State Budget Law 2027, which was passed today, Tuesday (29/9/2026).
"In the context of optimising state revenues, the Minister of Finance shall be authorised to conduct audits and/or special audits of state revenues, including audits and/or special audits in the context of tax refunds," reads Article 37 paragraph (1) of the 2027 State Budget Law.
In line with this authority, Minister of Finance, Suahasil Nazara, affirmed that tax refund management to be carried out by the government through the Directorate General of Taxes (DGT) will be conducted pursuant to the applicable regulations.
He also confirmed that tax refund management will be implemented without prejudicing the rights of taxpayers who have made a tax overpayment. The management is intended to ensure compliance by taxpayers submitting refund claims.
"The government respects all the rights of taxpayers submitting refund claims. At the same time, however, we also wish to ensure compliance regarding invoices, transactions and relationships between taxpayers that must be established to obtain a tax refund," said Suahasil.
For information, the government has recorded a decline in tax refund disbursements compared with last year. The total value of tax refunds to August 2026 reached IDR191.82 trillion, down 37% compared with the previous year.
The realised tax refunds comprised income tax refunds of IDR55.79 trillion, value added tax (VAT) and sales tax on luxury goods (STLGs) refunds of IDR134.32 trillion and other tax refunds of IDR1.71 trillion.
Irrespective of developments in disbursement values, tax refunds must be understood in their proper context as a mechanism for returning tax overpayments that constitute a taxpayer's entitlement. See: Reversing Paradigm of Tax Refunds as a State Fiscal Threat.
In the specific case of VAT, a tax refund is a consequence of the mechanism for crediting input VAT against output VAT to preserve the neutrality of VAT as a tax on consumption. See Urgency of Redesigning VAT Refund Mechanism in Indonesia
From a tax administration perspective, supervision of tax refunds is necessary to prevent unwarranted claims. However, supervision mechanisms must also maintain a balance between preventing abuse and fulfilling taxpayers' rights, including through a risk-based approach.
A number of publications also emphasise the importance of a prompt and accurate tax refund process to safeguard taxpayers' cash flow as well as the quality of tax administration. See How Should the Gov't Manage VAT Refunds?
Accordingly, the design of tax refund audits must ensure that high-risk claims receive adequate scrutiny without impeding the return of legitimate tax overpayments. See Re-examining Prepaid Tax Scheme as Root Cause of Tax Refunds (rig)