



Intangibles Disclosure Key to Preventing TP Disputes
SINGAPORE, DDTCNews - Intangible assets (intangibles) now account for more than 90% of global corporate value, with estimates reaching USD60–USD100 trillion, equivalent to two-thirds of world GDP (WIPO Global Innovation Index, 2025). Yet behind their massive commercial potential, intangibles transactions between affiliated companies have become a primary trigger of transfer pricing disputes.
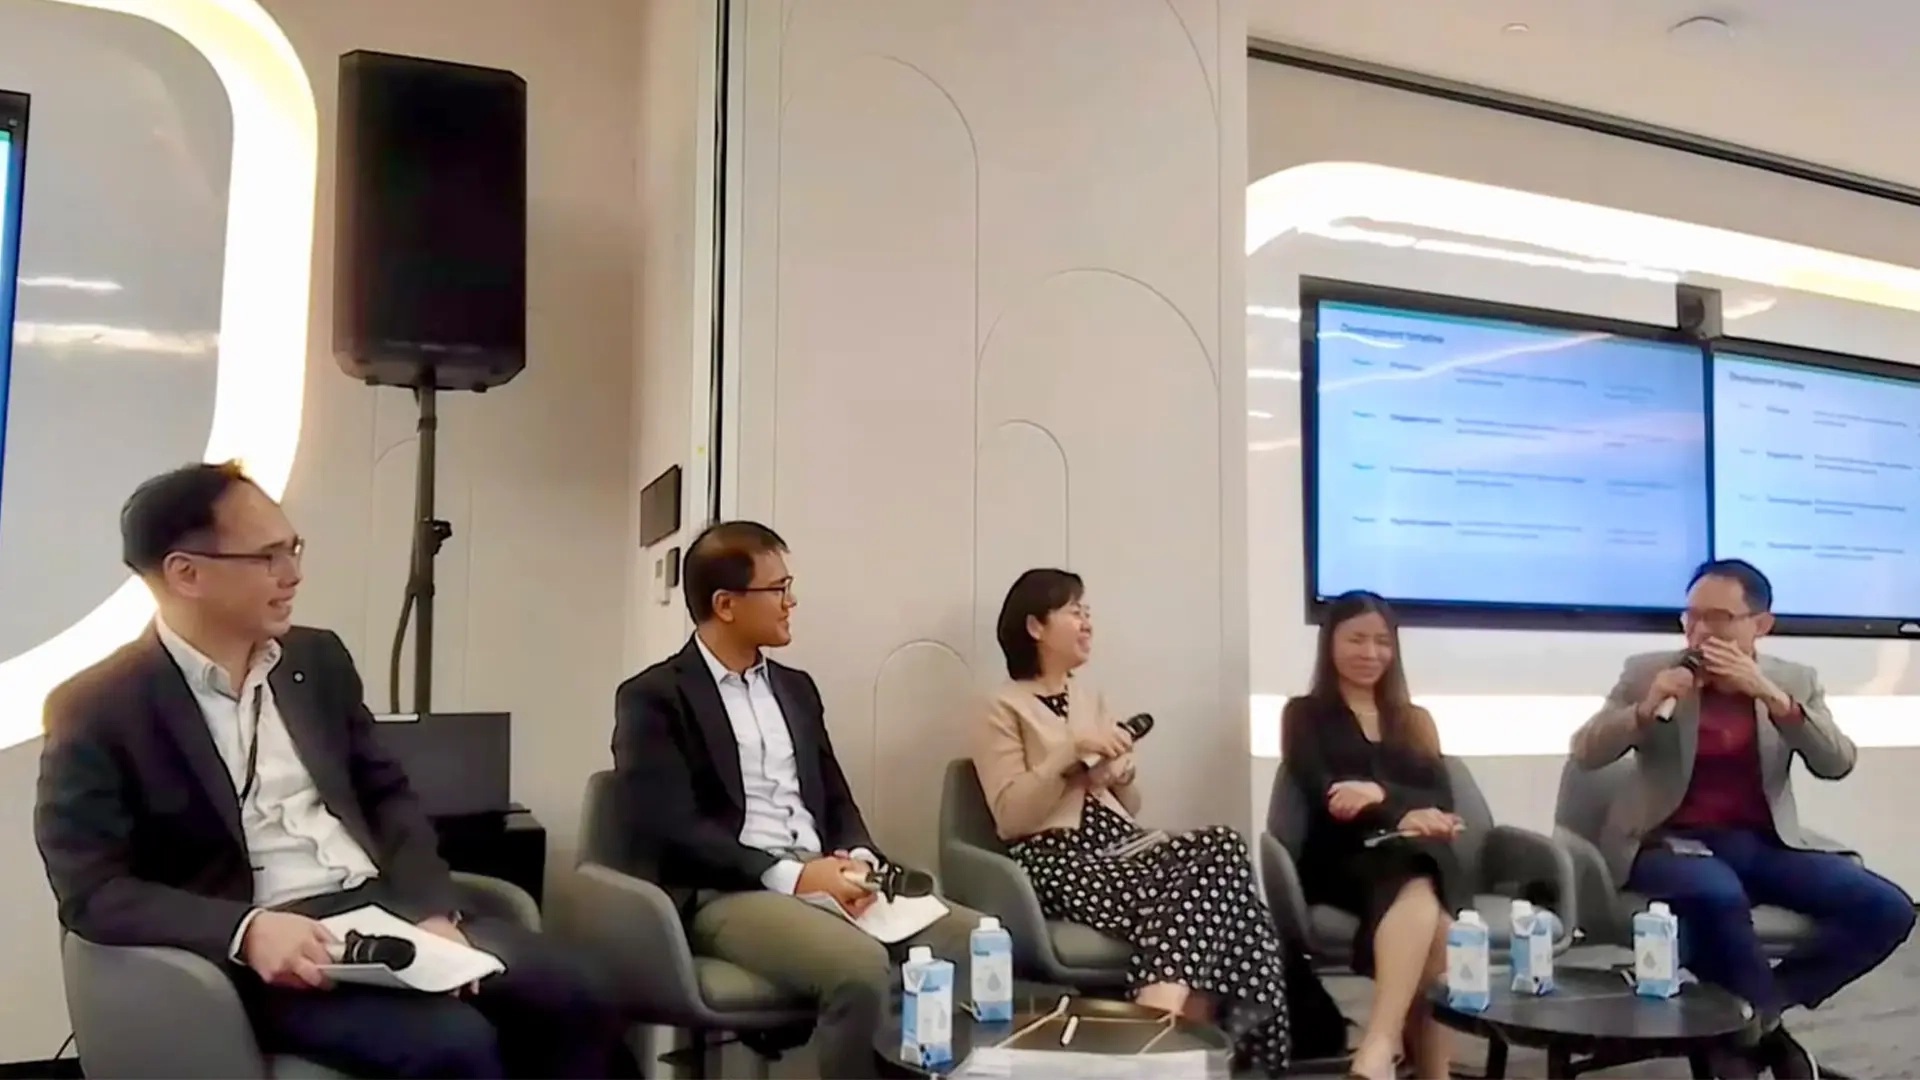
This dynamic was examined in depth during the executive programme Integrated IP, Valuation & Tax (IIVT), organised by the Tax Academy of Singapore and IPOS International.
One of the notable topics presented on the third day of the programme (7 October 2026), which carried the theme Module 3: Tax, Transfer Pricing, & Cross-Border Risk Management, was how the application of the intangibles disclosure framework (IDF) can be utilised by taxpayers as a preventive instrument to reduce the risk of transfer pricing adjustments before disputes arise at the tax court.
IDF: A Four-Pillar Preventive Framework
In their presentations, the speakers underscored a fundamental challenge in conventional financial reporting. Accounting standards such as IAS 38/IFRS strictly limit the recognition of internally generated intangible assets on the balance sheet. As a result, the real value built by companies through research and development (R&D), data governance and commercial networks is often not presented (off-balance sheet) and is treated merely as an operating expense.
To address this information asymmetry, Singapore launched the IDF in 2023 under the Singapore IP Strategy (SIPS) 2030, through IPOS and ACRA. The IDF provides a framework for presenting the value and governance of intangible assets in a structured, evidence-based manner to stakeholders. It should be noted, however, that the application of the IDF in Singapore is currently voluntary and does not replace existing accounting standards or regulations.
Underpinned by four key pillars known by the acronym SIMM (strategy, identification, measurement, management), the IDF can also serve as a structured means to assist taxpayers in identifying, documenting and aligning asset assessments and tax considerations with the underlying business strategy, commercial reality and value drivers, according to Richard Gooh, Master Tax Specialist at the Inland Revenue Authority of Singapore (IRAS).
The relevance of this framework is further affirmed in the IRAS e-Tax Guide on valuation reports for intellectual property (IP) rights under Article 19B of the Income Tax Act 1947. In that guidance on preparing independent valuation reports, required to demonstrate the fair market value of IP acquisitions, IRAS explicitly recommends the IDF framework. IRAS considers the IDF to provide practical guidance for companies in explaining and substantiating the role and economic contribution of intangible assets, such as patents, trade marks, copyrights and trade secrets, within their business models.
As such, what is the role of the IDF as a preventive measure against transfer pricing disputes?
First, as a structured management and documentation tool. The SIMM framework within the IDF functions as a structured management tool to help companies organise, identify, and document intangible assets systematically from business, legal and tax perspectives. This consistent commercial documentation becomes highly valid supporting evidence for a taxpayer's transfer pricing documentation, effectively locking in the business group's value creation story.
Second, aligning business, valuation and tax. The IDF framework ensures that IP strategy, valuation models and transfer pricing assessments are derived from the same business facts and commercial reality. This narrative consistency prevents tax authorities from unilaterally deconstructing business structures or reallocating profits.
Third, facilitating development, enhancement, maintenance, protection and exploitation (DEMPE) analysis. Through the measurement pillar, the IDF provides quantitative performance indicators. Although the disclosure of monetary values under the measurement pillar is optional, this pillar guides companies to present quantitative performance indicators and value drivers.
Evidence such as operational efficiency, customer retention rates, and capacity optimisation can be directly used to address the existence and economic benefit tests required by tax authorities.
Fourth, as a risk control mechanism. With the management pillar requiring companies to actively identify and manage intangible asset risks, the IDF enables taxpayers to compile intangible asset registers and carry out periodic evaluations of permanent establishment (PE) risks, withholding tax and transfer pricing adjustments when cross-border expansion occurs.
As a preventive shield, the IDF can help taxpayers build a defensible analysis by linking legal agreements, business models, intangible asset registers, value drivers, DEMPE facts, payment flows and risk controls. Companies that implement the IDF effectively will have significantly more transparent intellectual property governance.
This transparency can significantly reduce the risk of tax adjustments by tax authorities, as the full economic history of intangible assets has been recorded in a coherent and consistent manner from the outset.
What About Indonesia?
In the context of taxation in Indonesia, transactions involving royalty payments and IP/technical know-how licence fees between members of a multinational group are one of the primary triggers of disputes in tax audits and litigation. This is because tax authorities frequently question the existence and genuine economic benefit of the use of such intangible assets for the local entity.
The primary trigger for tax adjustments generally stems from taxpayers' inability to present substantial technical documentation and historical evidence. Taxpayers often struggle to demonstrate the proportional contribution of DEMPE analysis and to quantify the commercial value added that is genuinely enjoyed by the entity in Indonesia.
This is where the IDF presents itself as a technical solution. Through the four-pillar SIMM approach, the IDF can guide taxpayers to map business facts, value drivers and the allocation of DEMPE functions in a structured manner from the planning stage.
Through such evidence-based disclosure, taxpayers can detect and map internal risk gaps at an early stage. Where a potential difference of views regarding the arm's length rate of royalties or the classification of income is identified, taxpayers need not wait until the dispute stage, which is both costly and time-consuming.
Such risks can be resolved proactively through dispute prevention instruments, such as an advance pricing agreement (APA) or mutual agreement procedure (MAP).
The application of the IDF's SIMM framework gains ever-greater strategic momentum as the Directorate General of Taxes (DGT) beginning to introduce a cooperative compliance model. The principles of the measurement and management pillars within the IDF can be directly integrated as the foundation of a taxpayer's internal tax control framework (TCF).
This integration ensures that transfer pricing documentation presented to tax authorities is not merely a formal compliance exercise on paper, but rather a true and verifiable reflection of business reality.
Ultimately, this information transparency, supported by substantial evidence, not only provides legal certainty over intangible asset transactions, but also builds the credibility and trust of tax authorities in the level of taxpayer compliance.
Report from Singapore
For reference, this report was written by DDTC Consulting Senior Manager, Khisi Armaya Dhora, who attended the programme entitled Integrated IP, Valuation & Tax (IIVT): A Strategic Toolkit for Decision-Makers. The programme was held on 5–7 October 2026 in Singapore.
In addition to Khisi, DDTC Consulting Senior Manager, Muhammad Putrawal Utama, and DDTC Consulting Manager, Wulan Clara Kartini, also attended the IIVT programme. The participation of these professionals in the training forms part of the Human Resource Development Programme (HRDP) that DDTC consistently carries out.
Through this programme, DDTC provides its professionals with the opportunity to participate in various competency development programmes, both domestically and abroad. All costs associated with participation in the programme are borne by DDTC with no service bond attached.
DDTC Founder Darussalam stated that DDTC consistently provides its professionals with opportunities to enhance their competence through various education and training programmes, both domestically and abroad.
He noted that the participation of DDTC professionals in these various programmes is expected to broaden their perspectives whilst strengthening competence in keeping pace with developments in knowledge and tax practice at the global level. (dik)