



An In-Depth Look at US War Taxes
WHY have modern wars, such as the United States (US) conflicts in Afghanistan and Iraq following the 9/11 Tragedy, lasted so long that they have been dubbed forever wars?
Advances in technology and military strategy are considered to have reduced the burden of casualties, making war feel distant and operating largely behind the scenes.
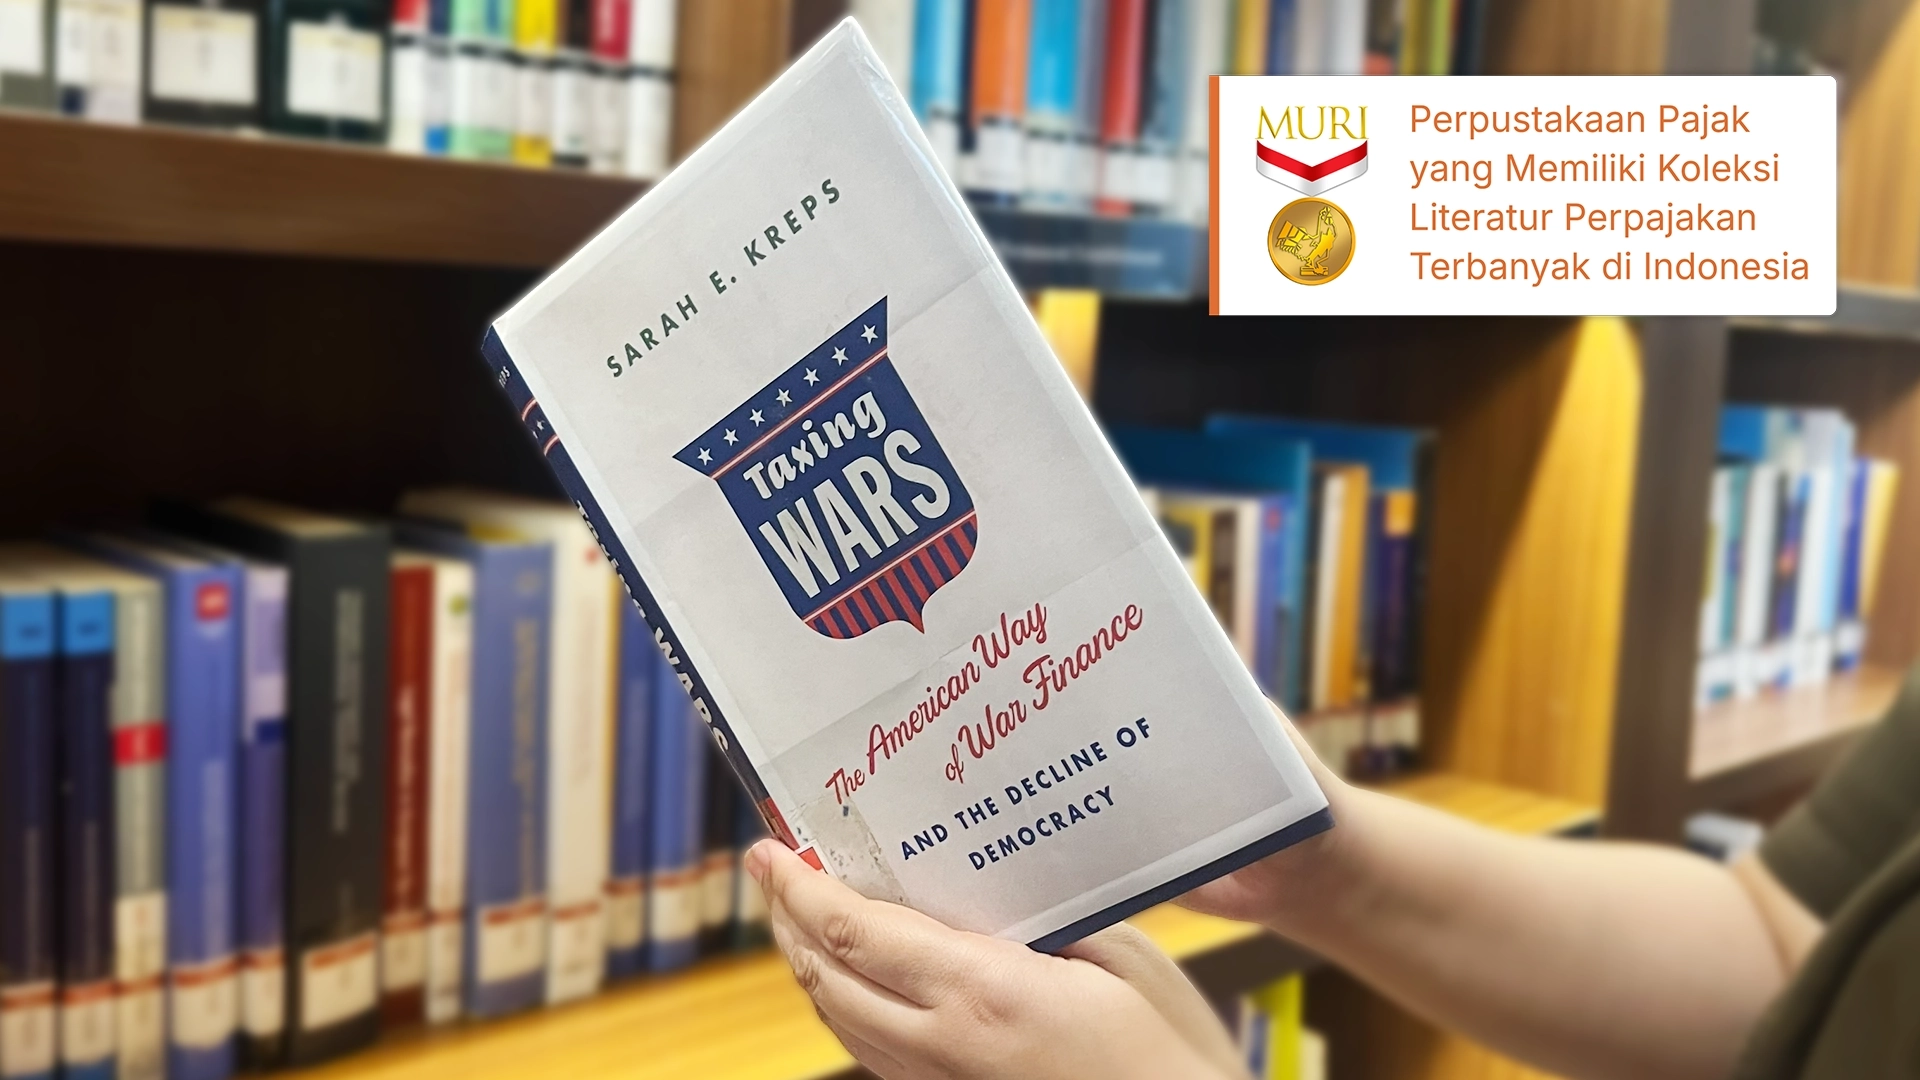
However, in the provocative book entitled Taxing Wars: The American Way of War Finance and the Decline of Democracy, Sarah E. Kreps reveals the wars conducted by the US as 'two sides of the same coin'.
On one side is the state's effort to reduce the burden of casualties (cost in blood), and on the other is how the state finances those wars (cost in treasure).
Published in 2018, this book presents historical and political-economy arguments concerning the US and modern democracies that have shifted dramatically from war taxes towards borrowing/deficit financing.
This shift conceals the war 'bill' from taxpayers' pockets, undermines public oversight functions and ultimately erodes the pillars of democratic accountability.
Kreps invites readers to traverse the long history of US war financing from the Revolutionary War era of 1789 through to the 21st century, dividing financing strategies into two principal eras.
First, the liberty bond wars era. From the American Civil War through to World Wars I and II, war was viewed as a life-or-death wager for the nation (absolute wars). The government spontaneously called upon its citizens for genuine 'fiscal sacrifice'.
War taxes were levied by raising income tax rates to their highest levels in US history, reaching a marginal rate of 95% during World War II. In addition, the government issued war bonds (liberty bonds) that were promoted through mass campaigns.
As a result, this fiscal sacrifice created fiscal citizenship, that is, a condition in which, when citizens' wallets were depleted by war, they were compelled to monitor the conduct of the war closely, demand clear outcomes and pressure the government to seek peace swiftly if the cost of war was no longer proportionate to its objectives.
Second, the hide-and-seek wars era. After 1945, limited wars, such as the Korean War, the Vietnam War, the Gulf War of 1991 and the wars in Afghanistan and Iraq no longer had definitive indicators.
In these modern wars, governments gradually abolished war taxes because they no longer possessed a 'noble cause' (collective cause) capable of mobilising the public to willingly bear fiscal sacrifice.
Aware that citizens were unwilling, governments ultimately chose the easy route of covering all war costs entirely through debt.
To explain why governments do not levy war taxes, Kreps introduces a relevant conceptual framework in modern public finance studies known as The Impossible Trinity.
In wartime conditions in the modern era, governments face three mutually contradictory demands. First, the need for military spending and operations (guns).
Second, public demands for social security, healthcare, and education (butter). Third, opposition to tax increases or new taxes (ceiling effect).
Using this framework, Kreps demonstrates how the US government's efforts to absorb enormous war costs into long-term debt have only succeeded in avoiding short-term risk.
One concrete piece of evidence is when the US government launched its invasion of Iraq and Afghanistan following the 9/11 Tragedy. At that time, the US president actually cut taxes as though nothing had happened, and all war costs were absorbed into debt and a special emergency budget reserve account known as overseas contingency operations (OCO).
As a result, the public assumed that the taxes they paid were sufficient to fund military spending as well as social security, and that the war being waged was 'free'.
Kreps also analyses the philosophical impact of taxation on democracy. Drawing on the thinking of Immanuel Kant and Adam Smith, the principal advantage of democratic states in preventing war lies in the direct involvement of their citizens in bearing the burden of war.
War tax collection is the most tangible form of state intervention in citizens' private lives and serves as a fiscal alarm.
When this fiscal alarm is switched off through debt financing, the bonds of accountability are severed, politicians' incentives are distorted and war becomes boundless.
In other words, the abolition of war taxes has transformed democracy from a system that restrains itself into one that allows war to proceed without oversight.
Kreps acknowledges that restoring income tax rates to those of the World War II era would be unrealistic in the modern political climate. However, through this book, she offers pragmatic solutions to redesign accountability, one of which is the introduction of war-specific levies, such as a counter-terrorism excise duty or a special war fuel tax surcharge.
In addition, Kreps proposes restoring the role of parliament to authorise war budget expenditure periodically and transparently, without it being concealed within emergency budget lines.
In closing, Kreps reminds us that taxes or 'bills' for every state decision will inevitably come due. If not paid by today's generation, they will be passed on to future generations, accompanied by the potential collapse of democracy.
Interested in reading this book? Please visit DDTC Library.
To date, DDTC Library holds a total of 5,078 literature collections supporting the study of taxation as a multidisciplinary field and has received the MURI record as the Tax Library with the Largest Collection in Indonesia on 10 July 2026.
Before visiting DDTC Library, the public may first confirm their visit via hotline: +62-21-2938-2700 or email: [email protected]. Visit the DDTC Library Instagram account for the latest information relating to tax literature. (dik)