



Taxing Sin, Abandoning Common Sense
Excise duty inserted into a shopping receipt when buying a can of fizzy drink or a packet of cigarettes is an instrument of the sin tax.
The logic of the sin tax appears straightforward and appealing to common sense; it even looks like the illusion of a win-win solution.
Goods deemed harmful to health or morality become expensive, discouraging people from buying them, nudging them towards healthier lifestyles, causing consumption to fall sharply and swelling the state treasury.
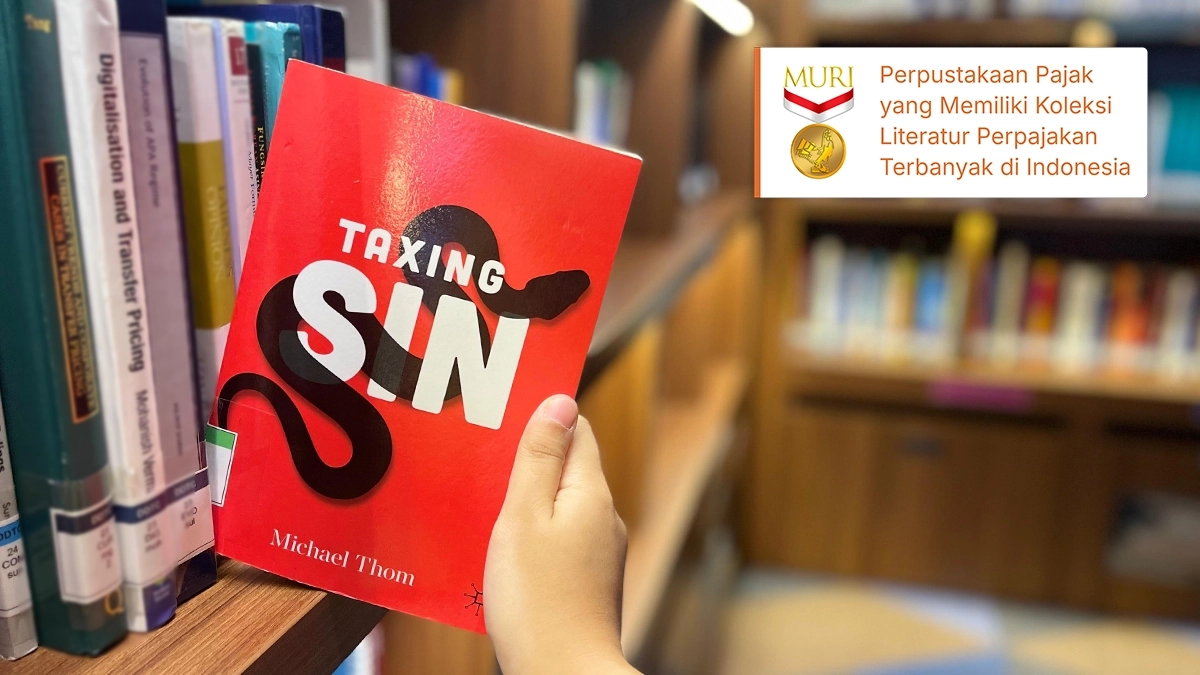
Yet, through the controversial book Taxing Sin, Michael Thom exposes the impropriety behind the sin tax that governments around the world hold up as a noble cause.
Published in 2021, the book argues that most sin taxes are not, in truth, an effective remedy, but rather a form of moral paternalism dressed up in the language of science that ultimately amounts to unjustified levying (fiscal-rent seeking).
To understand why the state is so obsessed with taxing its citizens' behaviour, Thom invites readers to revisit the long history of the relationship between morality and public finance.
In 16th-century Europe, the Roman Catholic Church sold sheets of paper bearing the signature of a religious authority as a form of absolution from sin in exchange for a sum of money (sale of indulgences).
This scandal of monetising sin ignited public fury, led by Martin Luther, triggering the wave of the Protestant Reformation and ending with the outright ban on the sale of those sheets of paper by the Pope of the time.
Strangely, centuries after religious institutions abandoned this practice, modern states have taken up the baton.
Modern governments seem to say: "Your lifestyle choices are wrong, unhealthy, and harmful to civilisation. However, if you are willing to pay a portion to the state each time you buy (a good), we will forgive you and allow you to continue."
Thom notes that levies on goods branded as sinful are not, in fact, a new phenomenon. Historically, this instrument was known as sumptuary laws.
In 1574, the Netherlands imposed a tax on alcohol to fund a war during the Spanish colonial period. Then, in 1604, King James VI of England levied a tax on tobacco, regarding smoking as a form of foolish vanity.
The Ottoman Empire also collected taxes on tobacco and coffee to finance the regular stipends of religious scholars in the 18th century. In the United States (US), federal taxes on alcohol and tobacco were introduced to fund the Revolutionary War, the War of 1812 and the Civil War.
However, according to Thom, there is a fundamental difference between past and present. Sin tax once targeted a handful of commodities and was temporary in nature. Today, sin tax has become a permanent component of national budgets, with the list of targeted goods continuing to grow.
Thom traces the ideological roots of this phenomenon to the progressive era of the 19th century that swept the US and Europe. At the time, individual freedom and free-market mechanisms were seen as sources of social disorder.
Citing the thinking of sociologist Edward Ross and economist E.R.A. Seligman, society too often falls victim to individual freedom, whilst the primary duty of the individual is to serve the state.
From this thinking was born the doctrine of paternalism: the conviction that technocrats, bureaucrats, and academics know far better what is best for society than society itself.
Added to this, Arthur Pigou's concept of the Pigouvian tax (1920), which created a special levy for goods falling into the category of sin, became a form of gentle nudge by the government to save society from its own weaknesses.
To expose this noble pretence of government, Thom analyses in depth four classic commodities targeted by sin tax: fizzy drinks, alcohol, tobacco and cannabis.
Taxes on packaged sugar-sweetened beverages are not, it turns out, the panacea that governments promised. From several reviews of the scientific literature, more than two-thirds of independent studies found no evidence of a causal relationship between soda consumption and a reduction in obesity rates.
When the price of a can of fizzy drink rises, many people substitute their calorie intake by purchasing chocolate milk, sugary coffee drinks and packaged fruit juices that are frequently excluded from taxable objects.
In the end, total daily calorie intake does not decrease; it merely drains the wallets of lower-income consumers.
Next, the case of alcohol. The narrative of externalities is frequently linked to treating all consumers as a homogeneous group. Yet the medical literature acknowledges that alcohol consumption at light to moderate levels can confer certain health benefits.
Social risks such as drink-driving accidents or domestic violence are not inherent to the alcohol itself, but to the behaviour of a small number of problem drinkers.
Thom cites research demonstrating that these problem drinkers are a group that is insensitive to price increases (inelastic). It is, in fact, the responsible casual drinkers who respond and reduce their consumption when alcohol is taxed.
As a consequence, alcohol tax becomes a punishment for millions of people who have no problem drinking, in pursuit of a handful of problem drinkers whose behaviour cannot, in reality, be changed through price instruments alone.
On tobacco tax, Thom uncovers a taboo dimension of public economic calculation that is rarely disclosed to the public: the calculation of long-term cost of living.
Those calling for higher tobacco excise duty always argue that smokers burden the health budget. However, several studies indicate that the shorter average life expectancy of smokers would, in the long run, actually save the state expenditure on pension funds and social security.
Further, when tobacco excise duty is set too high, smokers do not stop immediately. The majority, particularly those on lower incomes, instead purchase illicit cigarettes without an excise stamp.
The result is a thriving black market, a collapse in state revenue, overwhelmed law enforcement and a more dangerous product being consumed by the public with no quality-standard oversight.
In the chapter on cannabis, Thom traces an amusing political irony. For decades, governments warned the public that cannabis was a 'brain-destroying drug' that triggered various illnesses and crimes.
Yet, once the trend of decriminalisation spread, cannabis, previously branded as one of the gravest sins, was suddenly embraced, provided it was subject to high taxation.
High excise duty on legal cannabis makes legal market prices uncompetitive against illicit cannabis sold by street dealers, so legalisation loses its potency.
Government paternalism does not stop at traditional consumables. Thom specifically warns of an aggressive expansion in the definition of sin in the modern era.
Governments are preparing scientific justifications to tax new things deemed to be secular sins of the 21st century, such as a meat tax, a carbon tax, plastic bag levies and taxes on robots and AI.
This list of sins appears boundless, because the criteria used are extremely flexible. Whenever a state dislikes a particular lifestyle choice of its citizens, it need only fund simulation research to demonstrate harmful effects, then present a draft tax law to parliament.
Thom illustrates this in his analysis using the classic Baptists and Bootleggers model. Both have opposing motivations yet move together, forming an inseparable political coalition.
On one hand, experts and non-governmental organisations act as the Baptists, conducting exaggerated simulation studies on the dangers of a given good.
On the other hand, the government, which eagerly welcomes the findings of such studies, acts as the Bootleggers, i.e., the party that enjoys the tax remittances.
This is where the greatest impropriety of sin tax lies. Thom sets out the on-the-ground facts regarding the allocation of funds, which frequently deviate far from their stated purpose.
In several US states, funds are allocated to the procurement of books of accounts and gardening programmes, used to finance public fireworks displays, or simply absorbed to plug deficits in civil servants' pension funds.
Governments ultimately no longer control sin; they become addicted to the revenue from sin.
Further, Thom criticises the deeply regressive nature of sin tax. The heaviest burden falls on the shoulders of the poor; rather than achieving social justice, the tax becomes an instrument of structural impoverishment dressed up in false concern.
In closing, Thom delivers a firm message: judging other people's lifestyle choices, labelling them as 'sin', and extracting financial gain from that label is a policy that is flawed from the outset.
Thom reminds us that the world's major religions abandoned the monetisation of sin long ago, leaving matters of individual morality to the Creator.
“Don’t tax sin, forget it.”
Interested in reading this book? Please visit DDTC Library.
To date, DDTC Library holds a total of 5,078 literature items supporting the study of taxation as a multidisciplinary field, and has received a MURI Record as the Tax Library with the Largest Collection in Indonesia on 10 July 2026.
Before visiting DDTC Library, the public may first confirm via hotline: +62-21-2938-2700 or email: [email protected]. Visit the DDTC Library Instagram account for the latest information on tax literature. (dik)