



Official! Government Bears VAT on Christmas & New Year Air Tickets
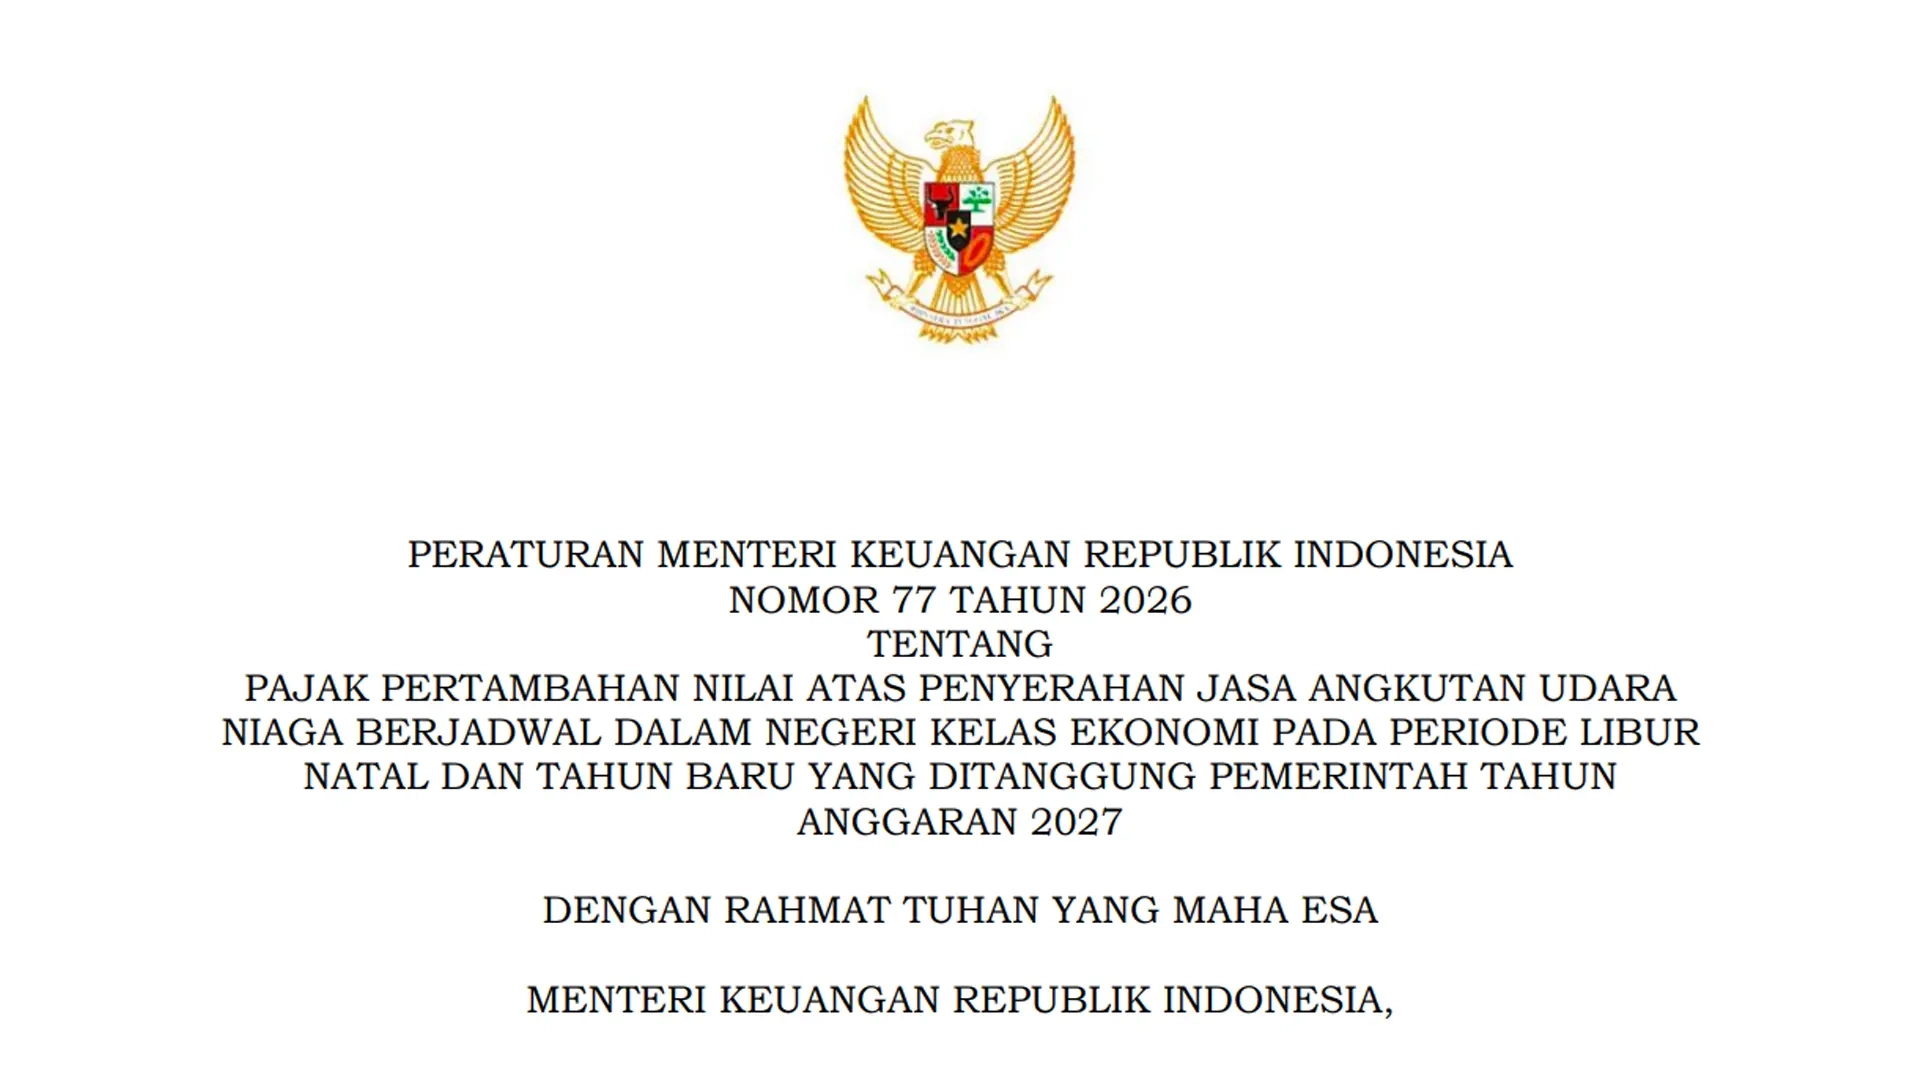
JAKARTA, DDTCNews – The government is again bearing value added tax (VAT) on domestic economy-class air tickets during the Christmas and New Year (Natal dan tahun baru/Nataru in Indonesian) holiday period. The government-borne (ditanggung pemerintah/DTP in Indonesian) VAT incentive is regulated under Minister of Finance Regulation (MoF Reg.) 77/2026.
Referring to MoF Reg. 77/2026, the government-borne VAT incentive is granted at 100%. The government-borne VAT is the VAT payable on the base fare and fuel surcharge. This incentive is provided to maintain people's purchasing power and stimulate the economy during the Nataru holiday period.
"The government grants a number of economic incentives, among others, in the form of the government-borne value added tax incentive for supplies of scheduled economy class domestic commercial air transport services for the 2027 fiscal year," reads the considering section of MoF Reg. 77/2026, as cited on Wednesday (21/10/2026).
The government-borne VAT incentive is granted for the ticket purchase period commencing 20 October 2026 through to 10 January 2027. However, the government-borne VAT incentive is only granted for the domestic economy-class flight period of 20 October 2026 through to 10 January 2027.
As an example, Mr Rerick purchases a domestic economy-class air ticket from Jakarta to Surabaya on 22 October 2026 for IDR1,136,756. The ticket is to be used for a flight on 22 December 2026. The ticket cost components are as follows:
|
|
base fare |
: |
IDR790,000 |
|
|
fuel surcharge |
: |
IDR121,600 |
|
|
IWJR fee |
: |
IDR5,000 |
|
|
passenger service charge |
: |
IDR119,880 |
|
|
VAT |
: |
IDR100,276 |
|
|
total |
: |
IDR1,136,756 |
Based on the above data, the VAT payable of IDR100,276 is borne in full by the government, as the ticket purchase date and flight date both satisfy the requirements of the applicable ticket purchase period and flight period for which the incentive is granted.
It should be noted that the government-borne VAT is only granted on the base fare and fuel surcharge. Accordingly, VAT on other cost components is not borne by the government.
VAT not borne by the government includes VAT on excess baggage and VAT on seat selection. (dik)