



DGT: L&B Tax-P5L Penalty Reduction as Stimulus, Streamlined Terms
JAKARTA, DDTCNews - The Directorate General of Taxes (DGT) has stated that the reduction or nullification of administrative penalties or fines for Land and Building Tax in the Plantation, Forestry, Oil and Gas Mining, Geothermal, Mineral and Coal Mining Sectors and Other Sectors (L&B Tax-P5L), as regulated under Article 27A of Minister of Finance Regulation (MoF Reg.) 71/2026, forms part of an economic stimulus package.
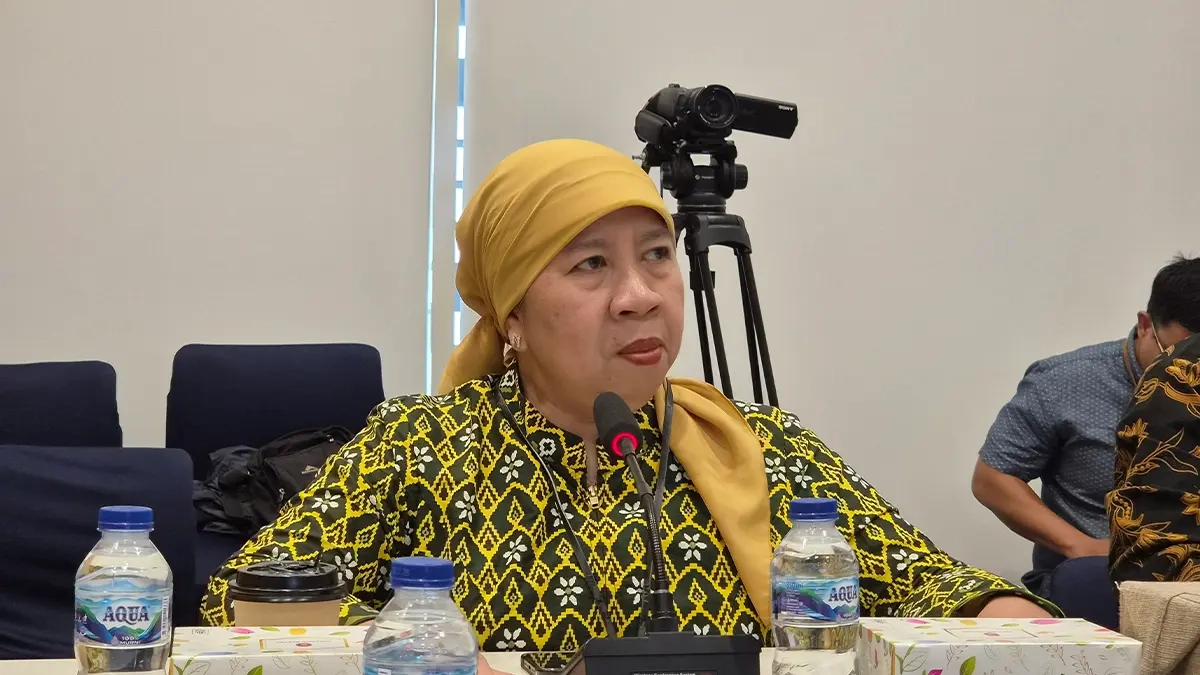
Director of Tax Dissemination, Service and Public Relations of the DGT, Inge Diana Rismawanti, stated that the stimulus is provided through simplified procedures for submitting applications for the reduction or nullification of administrative tax penalties. This is expected to ease the financial burden on taxpayers in the plantation, forestry, oil and gas mining, geothermal, mineral and coal mining sectors and other sectors.
"Article 27A of MoF Reg. 71/2026 serves as an economic stimulus in the context of accelerating economic growth and reducing the financial burden on taxpayers through broader simplification of the application process for the reduction or nullification of administrative penalties," she said on Tuesday (13/10/2026).
Inge also noted that, as a further facilitation, taxpayers are no longer required to prove substantively that a penalty arises due to negligence or not due to wilful misconduct.
She explained that under the former regulation, taxpayers were required to substantively prove that the administrative penalty imposed arose due to negligence or not due to wilful misconduct. That requirement was set out in Article 27 paragraph (3) of MoF Reg. 118/2024.
Under Article 27A of MoF Reg. 71/2026, taxpayers are no longer burdened with that substantive proof requirement. "Taxpayers are no longer required to substantively prove the grounds of negligence or absence of wilful misconduct, as restricted under Article 27 paragraph (3) of MoF Reg. 118/2024, as amended by MoF Reg. 71/2026," Inge claimed.
Inge explained that taxpayers need only satisfy the formal requirements stipulated under Article 23 of MoF Reg. 118/2024, as amended by MoF Reg.71/2026, to apply for the relief of L&B Tax-P5L administrative penalties.
"It is sufficient to fulfil the formal requirements pursuant to Article 23 of MoF Reg. 118/2024, as amended by MoF Reg. 71/2026, whilst remaining within the scope of Article 36 paragraph (1) subparagraph a of the General Provisions and Tax Procedures (GPTP) Law, namely on grounds of negligence or absence of wilful misconduct," she said.
Inge also reminded taxpayers that applications for the reduction or nullification of administrative penalties pursuant to Article 27A of MoF Reg. 71/2026 may be submitted no later than 1 October 2028.
It should be noted that the technical provisions and requirements for submitting applications for the relief of administrative tax penalties are further regulated under Director General of Taxes Decree KEP-239/PJ/2026.
For information, the government has inserted a new provision, namely Article 27A, which stipulates that the DGT may grant the nullification or reduction of L&B Tax-P5L administrative penalties to support the Indonesian economy. (rig)